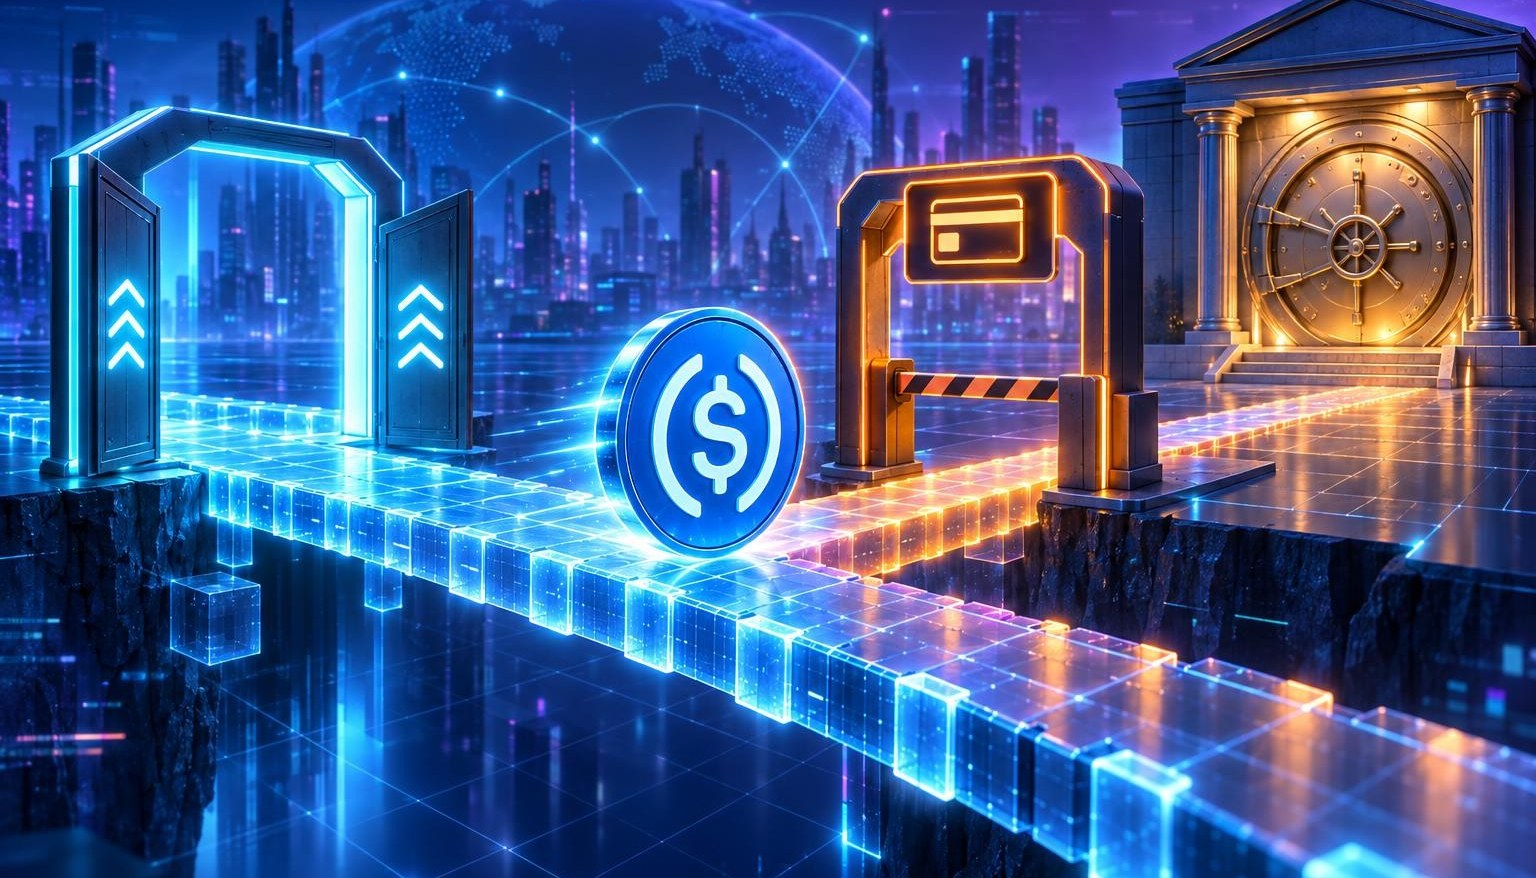
Samsung Wallet’s USDC transfers have no Samsung fee, but users who fund their accounts by credit card pay 4%, including when they use Samsung Pay. The accounts went live on November 5, 2026. A $100 card top-up carries a $4 fee before the user sends any USDC.
The feature lets eligible U.S. Galaxy users buy, hold, send and receive Circle’s USDC on Solana inside the app they use for cards and boarding passes. They do not need a separate crypto app or have to handle private keys. Samsung says about 82 million U.S. Galaxy devices are compatible, though the account has additional eligibility rules.
The free transfer starts after the funding decision
Samsung charges no fee to send USDC to another Samsung Wallet user in the United States or to a compatible outside crypto wallet. A receiving wallet or exchange can impose its own charge. The price of a transfer therefore depends on more than the fee shown by the sending app.
- Credit-card top-up: 4%, including when the card is used through Samsung Pay.
- USDC wallet transfer: No Samsung fee to another U.S. Samsung Wallet user or a compatible crypto wallet.
- Bank or debit-card withdrawal: A fee applies when users move funds out.
Consider a user who adds money by card, sends USDC and later withdraws to a bank account. The card fee applies when the money enters the account, and a withdrawal fee applies when it leaves. The wallet-to-wallet transfer between those steps carries no Samsung fee.
Samsung Wallet also supports sending funds to qualifying bank accounts in more than 60 countries, where recipients may receive local currency. Fees vary by destination. A user sending money to a bank recipient must check that route’s price rather than treating it as a USDC transfer to a compatible crypto wallet.
The wallet removes private-key work, while Bastion and Coinbase hold the USDC
Bastion provides the stablecoin account and transfer infrastructure. Coinbase acts as Bastion’s sub-custodian and safeguards the USDC through Coinbase Prime Vault. That arrangement lets users send USDC from Samsung Wallet without managing the keys that control a crypto wallet.
Samsung’s disclosures describe the account as a crypto wallet, not a bank account. The distinction matters because the balance sits behind a familiar payment app: Bastion and Coinbase hold the USDC, while moving funds to a bank is a separate transaction with a fee.
What they lacked was a way to reach the mainstream.
Lily Liu, president of the Solana Foundation
Liu was speaking about stablecoins after a decade of use. Samsung’s approach puts them in an app already installed on compatible devices, removing the step of setting up a separate crypto app. It does not remove the charges attached to funding or withdrawing.
Access and fees decide who benefits now
The service is open to U.S. residents aged 18 or older with Galaxy devices running Android 13 or later. New York residents are excluded. The compatible-device count describes potential reach; those age, location and software rules decide who can open an account.
The first top-up offer changes one user’s entry cost
A new user whose first top-up is at least $50 can receive $25 in USDC. The stated 4% fee on a $50 credit-card top-up is $2. That offer changes the first transaction for a qualifying user, while later card top-ups still carry the regular funding charge.
For someone who already has a way to fund the account and wants to send USDC, the absence of a Samsung transfer fee is the main price point. A person who needs to use a credit card, withdraw to a bank or send local currency abroad has to account for the charges at those steps. Bastion and Coinbase handle the account and custody behind transactions started in Samsung Wallet.
Checkout payments are Samsung’s next stated test
Samsung announced its USDC transfer plan on October 7. It has also said it expects to explore online and in-store stablecoin payments, along with expansion to other markets subject to local rules. Those checkout uses would add a payment step to a product currently described through its funding, transfer and withdrawal routes.